When a Real Estate Scam Looks Completely Normal
The most effective real estate scams aren’t always the obvious ones. They’re the ones that look like a normal part of buying or selling a home.
Buying or selling a home requires a substantial amount of trust.
During a transaction, you’ll communicate with your real estate agent, a title or settlement company, inspectors and other professionals. If you’re financing the purchase, your lender becomes another major part of that process.
You’ll sign documents, provide personal and financial information, meet deadlines and move a substantial amount of money.
That’s all part of a normal real estate transaction.
It’s also what creates an opportunity for fraud.
A scammer doesn’t necessarily need an elaborate story. Sometimes all they need to do is insert themselves into a process that already involves emails, phone calls, documents, payment instructions and people you may have only recently met.
The communication looks normal because it’s designed to look like something you were already expecting.
This is something I talk about with my clients because I don’t think buyers and sellers should be afraid of the process. But I do think they should understand where the vulnerabilities are and know what deserves a closer look.
Sometimes the Scam Starts Before the Transaction
Fraud can begin before an offer is ever written.
A legitimate property listing can be copied, including the photographs and description, then reposted with someone else’s contact information. The person responding to the inquiry may have no connection to the property at all.
From there, the goal may be a deposit, application fee or other payment. In other cases, the real target is personal information: a Social Security number, driver’s license, date of birth, employment information or financial details that can be used for identity theft.
The Federal Trade Commission has specifically warned about scammers copying legitimate rental listings, replacing the contact information and using those listings to collect money or personal information.
Although rental scams are a common example, the larger lesson applies anytime you’re dealing with a property or someone claiming to represent one.
Before sending money or sensitive information, make sure the property is actually available and the person offering it has the authority to do so.
A professional-looking listing, website or email proves very little by itself.
Once You’re Under Contract, Fraud Can Be Harder to Spot
Once a buyer is under contract, requests for documents, information and money become part of the process.
I sometimes joke with my clients that once we get a home under contract, it can feel like everybody suddenly has their hand out.
Your lender needs documents. Inspections need to be scheduled and paid for. The title or settlement company becomes involved. There are deposits, appraisal costs and eventually the funds needed for closing.
Those requests are legitimate and expected.
That normal activity is exactly what can make a fraudulent request difficult to recognize.
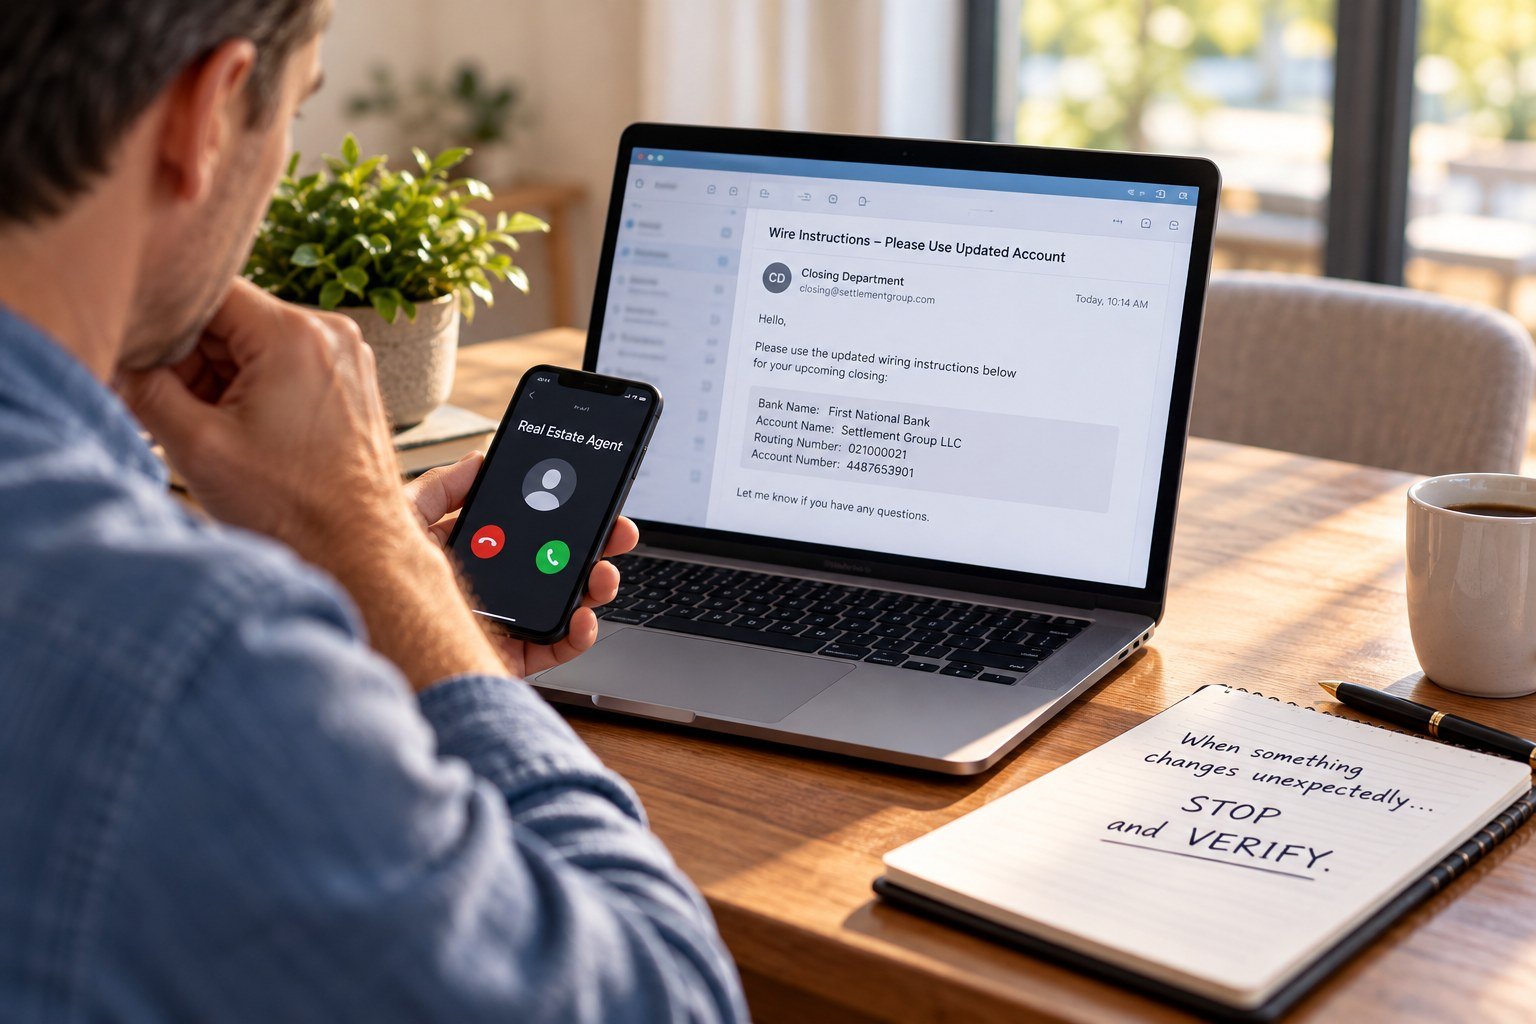
Suppose you receive an email that appears to come from the title company. The company name is correct. The person’s name is familiar. The message references the property you’re buying.
But something has changed.
The wiring instructions are different. You’re suddenly being told to send money to another account. The email address is slightly different. Or someone you haven’t dealt with before has stepped into the conversation and is giving you new instructions.
That change deserves your attention.
It doesn’t prove the message is fraudulent. It does mean you’re about to send a significant amount of money based on instructions that are different from what you expected.
Stop before you send it.
Call the title company using a number you already know is legitimate. Call your agent. If the request supposedly involves your lender, contact the lender through the information you already have.
Most importantly, don’t use the contact information inside the questionable message to verify the message itself. If you’re trying to determine whether a communication is legitimate, verification needs to come from a source you already trust.
The FBI has documented this exact type of scheme: a homebuyer receives what appears to be a legitimate message from a title company with instructions for wiring money, but the message is fraudulent and the money is sent to criminals instead.
Sometimes the Target Is Your Information, Not Your Money
Real estate transactions require sensitive information.
If you’re financing a home, your lender will need financial documents, employment information, identification and other personal details. Other professionals involved in the transaction will need information from you at different stages as well.
That is normal.
What matters is who is asking, why they need it and whether they actually belong in the transaction.
If you’ve already provided sensitive information to your lender and an unfamiliar person suddenly contacts you asking for your Social Security number, bank information or date of birth, find out who they are before handing anything over.
If you’re my client, that’s exactly the kind of situation where I want you to call me.
You’re not bothering me by asking.
I’d much rather spend five minutes confirming that everything is legitimate than have a client take an unnecessary risk because they didn’t want to make a phone call.
Sellers and Property Owners Face Different Risks
Buyers aren’t the only targets.
Seller impersonation fraud occurs when someone pretends to own property they don’t actually own and attempts to sell it.
Public property records can provide enough information for someone to identify an owner and begin constructing a convincing story. Virginia studied this issue specifically and found that these schemes primarily target vacant or unoccupied properties and properties without a mortgage. The study also identified tactics such as rushed transactions, cash-only sales and remote communication as patterns that can appear in fraudulent transactions.
That doesn’t mean an out-of-state seller is suspicious. A cash transaction isn’t suspicious. A seller who prefers email isn’t suspicious.
Context matters.
When several unusual details begin stacking up — extreme urgency, below-market pricing, reluctance to speak directly, resistance to identity verification or an insistence that everything be handled remotely — the transaction deserves a closer look.
For property owners, especially those who own vacant land, second homes or other property they don’t visit regularly, unexpected notices or activity involving that property should never be ignored.
Urgency Works Because Real Estate Already Has Deadlines
Real estate has real deadlines.
Offers expire. Inspection periods end. Lenders need documents. Closing dates are set.
That makes urgency feel normal.
Someone trying to commit fraud can take advantage of that by pushing a buyer or seller to act before there’s time to question what’s happening.
The answer isn’t to distrust every deadline. It’s to remember that no legitimate deadline prevents you from confirming where your money is going or who is asking for your personal information.
A few minutes spent asking a question is a reasonable trade when the stakes are high.
You Don’t Need to Recognize Every Scam
Fraud changes.
Names change. Websites change. Email addresses change. The story changes. The explanation for why money needs to be sent somewhere changes.
Trying to memorize every possible scam isn’t realistic.
A better approach is to understand what normally belongs in a real estate transaction well enough to recognize when something doesn’t.
Pay closer attention when:
- Someone you don’t recognize suddenly becomes involved.
- Payment or wiring instructions change unexpectedly.
- You’re asked for sensitive information without understanding why it’s needed.
- A familiar person contacts you through unfamiliar contact information.
- A deal seems dramatically different from what the market would normally support.
- Someone pressures you to act before you have time to understand what’s happening.
- Several details simply don’t add up.
None of those things automatically proves fraud.
They’re reasons to ask another question before moving forward.
What I Tell My Clients
Once we’re under contract, I want my clients to understand who is involved in the transaction and what they should expect next.
Know how to reach your agent, lender, title or settlement company and the other professionals working on your transaction. Save their legitimate contact information before you need it.
That gives you a reliable point of reference if something unexpected happens.
If a questionable email supposedly comes from the title company, you already know how to reach the real title company. If an unfamiliar person claims to be working with your lender, you know how to reach your lender directly.
And if something simply doesn’t make sense, call your agent.
You don’t need to become a detective. You need to know who your people are and how to reach them.
If the Money Has Already Been Sent, Act Immediately
If you believe money was sent because of fraudulent instructions, contact your bank or financial institution immediately.
Tell them you believe the transfer was fraudulent and ask them to contact the receiving financial institution. Alert the professionals involved in the transaction as well and report the incident to the FBI’s Internet Crime Complaint Center, commonly known as IC3. The FBI specifically advises victims of fraudulent transfers to act quickly.
If personal identifying information was compromised instead of money, take that seriously too. Contact the appropriate financial institutions and take steps to protect your accounts and identity.
At that point, speed matters.
Awareness, Not Paranoia
Most real estate transactions move from contract to closing without anyone encountering fraud.
The point of this isn’t to make buyers and sellers suspicious of every email, phone call or professional involved in the process.
It’s to recognize that real estate brings together substantial amounts of money, sensitive personal information, deadlines and multiple people working toward the same closing.
That creates opportunity for someone who doesn’t belong in the transaction.
Protecting a client’s interests means more to me than negotiating price and terms, writing an offer or putting a home on the market. It also means helping my clients understand what’s happening, who is involved, what should come next and when something deserves a closer look.
You don’t need to recognize every scam.
You need to understand the transaction well enough to recognize when something doesn’t belong.
And sometimes the most useful question you can ask is also the simplest:
Does this make sense?
If it doesn’t, find out why before you move forward.